Nations continue their gold-buying streak in September 2026: Why build bullion reserves?
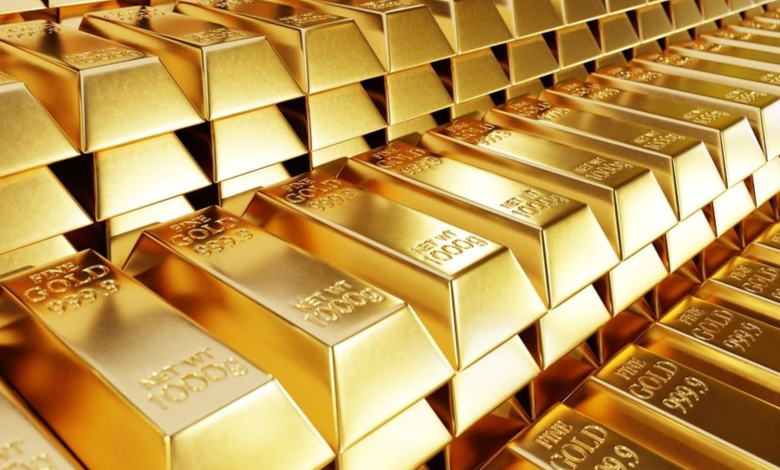
DAR ES SALAAM: TRADITIONALLY, governments paid less attention to gold in their international reserve strategies, focusing, instead, on accumulating foreign currencies such as the US dollar and heavily investing in government bonds.
Recently, this trend has reversed as central banks globally are increasing their gold reserves, reflecting a shift in how they view what makes a national reserve secure and robust.
This is not merely a story about increasing gold prices; it also highlights themes of economic independence, diversification and safeguarding against an unstable global financial system.
The scale of this shift is considerable. According to the World Gold Council, central banks have added around 1,000 tonnes of gold each year over the past four years, about double the rate of the previous decade.
According to their 2026 survey, 89 per cent of reserve managers expect global central-bank gold reserves to rise within the next year, and a record 45 per cent expect their own institutions to increase holdings.
Central banks are therefore treating gold less as an old-fashioned asset and more as a strategic instrument. Gold as insurance against geopolitical uncertainty.
A key factor fuelling renewed interest is geopolitical risk. Conflicts, sanctions, trade disputes, shipping disruptions and tensions among major powers demonstrate how political decisions impact financial connections.
Foreign exchange reserves held in other countries’ financial systems could be subject to sanctions, restrictions or changes depending on shifting international relations.
Gold is unique because it isn’t someone else’s liability. It has no issuer, isn’t dependent on a foreign government’s credit, and can be directly held by the reserve manager.
While this does not make gold entirely risk-free, it provides governments with an asset that can assist in diversifying their holdings amid uncertain geopolitical conditions.
The 2026 survey by the World Gold Council shows that central banks increasingly view gold as a strategic asset, influenced by economic and geopolitical uncertainties, inflation, and the importance of diversifying reserves.
The US dollar remains dominant, although diversification is increasing. A rise in global bullion reserves does not imply the decline of the US dollar.
The dollar continues to play a key role in global trade, finance, payments and foreign-exchange reserves. However, reserve managers are increasingly focused on lowering excessive concentration in any one asset or currency.
Gold provides a way to diversify reserves. The main distinction is between de-dollarisation and reserve diversification. A nation can hold substantial dollar reserves while increasing gold holdings. For emerging economies, this strategy offers additional protection against currency volatility, external funding difficulties and global financial crises.
Inflation is an important factor to consider. Historically, gold has proven to be a dependable store of value. When investors are concerned about inflation, currency devaluation or diminishing purchasing power, the demand for gold typically increases.
These concerns have intensified in the current environment, with governments experiencing significant fiscal pressures, changing interest rate forecasts, commodityprice volatility, and rising geopolitical risks.
The World Gold Council predicts that by the end of 2026, ongoing factors such as geopolitical tensions, bond market uncertainties, potential monetary easing and US dollar pressures will continue to increase gold investment demand. As a result, central banks might consider gold a key part of an overall portfolio risk-management approach.
Evidence from China and emerging markets underscores the trend’s strategic importance. The People’s Bank of China reportedly added 40 tonnes of gold reserves in the first half of 2026 and continued purchases in July. Similarly, Poland, Uzbekistan and Kazakhstan have been significant gold accumulators.
The importance goes beyond the amount of gold bought; it shows that emerging economies are progressively considering reserve composition crucial for their economic stability. For instance, in 2025, Poland added 102 tonnes of bullion gold, totalling 550 tonnes, which makes gold about 28 per cent of its reserves.
This emphasises an important aspect of the current bullion cycle: Central banks are not just buying gold to prepare for an immediate crisis but are building their resilience proactively. Gold is shifting from being merely a safe haven to a strategic asset. Therefore, calling gold simply a “safe haven” does not fully capture its role.
Gold plays several important roles simultaneously. It provides diversification, helps preserve longterm value, enhances confidence in national reserves, and offers liquidity in times of financial stress. Moreover, it can serve as collateral in certain financial transactions. Of particular interest is the growing attention to where gold is stored.
In September 2026, the Netherlands revealed that it moved around 86 tonnes of gold from New York and Ottawa to London, citing better liquidity, easier trading, and increased readiness for severe crises. This highlights that reserve managers are now paying more attention not just to the amount of bullion gold they hold but also to its storage location and accessibility in times of crisis.
The emerging strategy isn’t solely about buying more gold; it also involves buying, diversifying, securing and ensuring ongoing access to it. Nevertheless, the bullion approach has its limitations, and there’s an important caveat to bear in mind.
Gold does not generate interest or dividends. Holding large amounts can incur opportunity costs when interest rates are high. Moreover, gold prices tend to be highly volatile. If a central bank buys heavily at a market peak, it could face substantial valuation losses if prices subsequently fall.
Gold cannot replace foreign-exchange reserves because countries need currencies like dollars and euros to pay for imports, handle external obligations and intervene in forex markets. As a result, the best approach is typically to diversify portfolios rather than exchanging one reserve asset for another.
The 2025 experience highlights this complexity, as central banks bought 863 tonnes of bullion gold worldwide, much more than the 473 tonnes average from 473 to 2021 but still less than the over 1,000 tonnes bought annually in each of the past three years.
What does this mean for Africa? What does this mean for Tanzania? The continent must closely monitor this global trend given its substantial gold resources. However, many African economies remain vulnerable to exchange-rate fluctuations, external financial shocks and commodity-price swings.
Gold-producing countries can improve how they link mineral output to national reserves. However, increasing bullion reserves requires not only strong governance but also transparency.
Key questions involve the amount of gold to hold, the optimal storage location, whether the central bank should purchase domestically produced gold, how to value gold reserves and what proportion should be in bullion. Additionally, ways to ensure transparency and prevent leaks in the gold supply chain are also considered.
These questions pertain to institutions and policies rather than just mining. In Tanzania, the global rise in official bullion holdings is especially significant, as gold is among the country’s key mineral exports.
The country could enhance its strategic benefits from the gold sector by improving links between gold production and the formalised gold trade, refining processes, foreign exchange management and reserve building.
The aim should not be to convert all gold production into central-bank reserves, since Tanzania still needs foreign currency for imports and international transactions. Instead, policymakers could focus on creating a sustainable long-term strategy where a portion of domestically mined gold, when economically viable and consistent with reserve management objectives, helps strengthen the country’s reserves.
This also highlights the need for continued efforts to formalise artisanal and small-scale mining, improve traceability, increase domestic value addition and reduce illegal gold flows. The Bank of Tanzania’s recent increase in gold bullion holdings suggests gold is playing a larger role in reserve management.
This signifies a new approach to economic security. The global rise in bullion reserves shows a change in government perspectives on economic safety. In the past, the emphasis was mainly on foreign currencies, sovereign bonds and international financial connections.
The evolving model is increasingly diverse, blending currencies, bonds, gold and other liquid assets to boost resilience against geopolitical, financial and economic shocks. This does not mean that the world is abandoning the dollar or that gold will supplant traditional reserve assets. Rather, central banks appear to stress that over-concentration creates risks, while diversification provides greater flexibility.
This could be the main lesson from the global bullion trend. As the world grows more uncertain, with geopolitical tensions, trade fragmentation, sanctions, currency fluctuations and unpredictable financial circumstances gold is being reconsidered not as a relic of the past but as a crucial strategic reserve for facing the future.
In countries such as Tanzania, the emphasis has moved from simply measuring gold production to finding ways to transform gold wealth into better financial resilience, stronger reserves, greater economic value and enhanced national economic security.