Connecting Tanzania: How local collaboration is powering the country’s digital economy
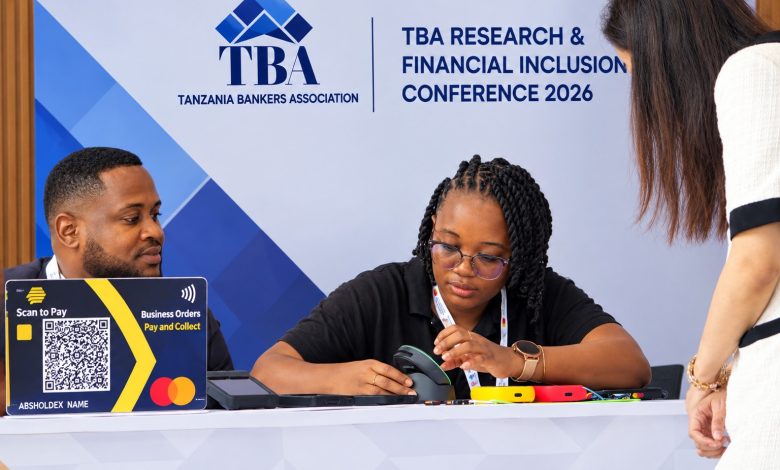
As the Tanzania Bankers Association concluded its Research and Financial Inclusion Conference in Zanzibar, Shehryar Ali, senior vice president and country manager for East Africa and Indian Ocean Islands at Mastercard, reflects on how banks, fintechs, mobile operators and technology companies are combining their complementary strengths to widen access to secure digital financial services, and why the next chapter of Tanzania’s growth will be written locally.
Few markets have moved as quickly as Tanzania. The country now counts more than 75 million active mobile money accounts, served by close to two million agents. Formal financial inclusion has reached 76% of adults, up from 65% in 2017, and nine in ten Tanzanians live within five kilometers of a financial access point.
None of that was built by one institution. It was built by many, each contributing something the others could not. Mobile network operators reached people no branch network ever would. Banks extended into wallets and agent networks. Fintechs solved narrow problems exceptionally well. The Bank of Tanzania created room to experiment while holding the system to a standard, and delivered shared infrastructure such as the Tanzania Instant Payment System. Global technology partners connected all of it to the rest of the world.
“Tanzania did not import its digital economy. It built one,” says Ali. “So our job is not to walk in with a solution built for somewhere else. The people building here read this market better than we ever will. What we bring is technology, security and global reach. What they bring is everything else.”
Enabling the enablers
That principle shows up most clearly in Mastercard’s work with Tanzania’s mobile money providers, which remain the front door to the financial system for most Tanzanians.
In November 2025, Mastercard and Axian Digibank & Fintech announced a collaboration spanning five African markets, including Tanzania through the Mixx brand. The collaboration brings virtual and physical cards, mobile wallet and digital banking services, and merchant payment solutions to consumers, entrepreneurs and small businesses. Customers can activate a card, top up an account, watch transactions in real time and pay across borders without leaving the app they already use.
Earlier, Mastercard worked with Tigo and Selcom to give Tigo Pesa customers a virtual Mastercard generated straight from their wallet, by USSD or in the app. The significance is easy to miss. A trader who has never held a bank account can create a card in under a minute and buy inventory from an international supplier the same afternoon.
Through its collaboration with Airtel Africa, Mastercard connects Airtel Money customers across 14 markets, Tanzania among them, to a cross-border remittance service reaching wallets and accounts in more than 145 countries, alongside virtual card capabilities that open up online merchants worldwide.
“Each of these collaborations starts in the same place, which is a real customer problem,” Ali says. “A parent who needs school fees to arrive today rather than next week. A shop owner who wants to buy stock from an international supplier without carrying cash. A young entrepreneur who wants to sell to customers she will never meet. The technology only matters if it answers one of those questions.”
From access to opportunity
Access, however, is not the same thing as opportunity. Tanzania’s small and medium enterprises make up the overwhelming majority of businesses and a substantial share of national output, yet they still account for barely a fifth of outstanding bank lending.
Closing that gap requires the same combination of strengths. Working with NMB Bank, Mastercard supported Africa’s first rollout of QR Pay by Link, allowing a vendor with no card machine and no capital to spare to accept a card payment through nothing more than a link or a QR code. The two also introduced a traders’ card built for businesses buying from China, Turkey, the UAE and Nigeria.
The commercial benefit is immediate. The longer-term benefit is quieter, and arguably larger. Every digital payment leaves a record, and a record is what a lender needs before it can price risk. Businesses that were once invisible to the formal system begin to acquire a track record.
“Digitizing a payment is the visible part,” says Ali. “Building a credit history is the part that changes a business’s future. That is why we care as much about what a transaction leaves behind as about the transaction itself.”
Trust as the foundation
None of this scales without trust. As more Tanzanians and more small businesses come into the digital economy, the responsibility to protect them grows with it, and that responsibility cannot rest with the customer.
Mastercard applies the same security architecture in Tanzania that it applies globally, from tokenization to AI-driven fraud detection, and works with local partners to extend those protections across the ecosystem. It also invests in the less visible work of standards, interoperability and shared rails, which is what allows something built for one wallet to reach a whole market.
“Security is not something you bolt on at the end,” Ali says. “Think about what happens when someone loses money on their first digital payment. They go back to cash, and it can take years to win them back.”
Built here, for here
The conversation in Zanzibar earlier this month kept returning to the same theme. The agenda was not simply more capital for small businesses. It was credit infrastructure, shared data and fairer ways to assess a business that is rich in history and short on collateral, all of which demand cooperation between institutions that have historically worked apart.
“The exciting part of this market is that the ambition is local,” Ali says. “Tanzanian banks, Tanzanian fintechs and Tanzanian operators are designing for Tanzanian customers, and they are getting it right. Our job is to make sure they have world-class technology behind them and that what they build can reach beyond these borders. Nobody grows a digital economy alone, and nobody should have to.”