Africa’s gas opportunity extends beyond LNG exports
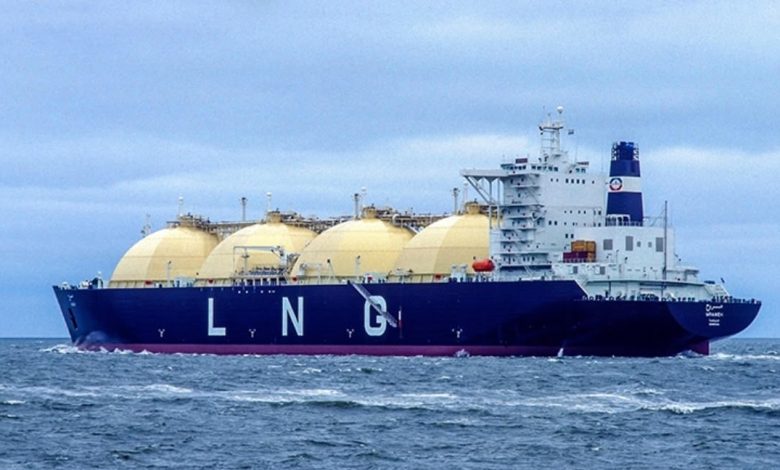
AFRICA: AFRICA is approaching a pivotal moment in its gas industry. The next phase of growth will depend not only on exporting liquefied natural gas (LNG) to global markets, but also on using gas to generate electricity, power industries, expand trade and strengthen energy security across the continent.
The opportunity is considerable. Gas accounts for about 25 per cent of global primary energy supply, compared with just 17 per cent in sub-Saharan Africa, excluding North Africa, according to the Energy Institute’s Statistical Review of World Energy.
After years of uneven progress, the region is positioning itself for a significant expansion of gas production and consumption. The prospects will be a key focus of discussions at Africa Energy Week 2026. Yet the timing presents both an opportunity and a challenge.
A major wave of new LNG capacity is expected to enter the global market over the coming years, led by the United States but with African producers, particularly Mozambique, also preparing to expand.
The International Energy Agency expects more than 330 billion cubic metres a year of additional global LNG export capacity to come online between 2025 and 2030 from projects already under construction at the start of 2025.
The scale of this expansion could reshape global supply and pricing, although project delays and geopolitical disruptions may alter the outlook.
For African producers, the challenge will be to secure markets, attract investment and ensure that new projects deliver benefits beyond export earnings. At the same time, disruptions to oil and LNG supplies through the Strait of Hormuz have highlighted the risks of relying on concentrated energy supply routes.
Diversifying production geographically and reducing exposure to geopolitical chokepoints have consequently become more important to energy-importing countries. Sub-Saharan Africa has an opportunity to contribute to that diversification.
Nigeria and Mozambique are particularly well positioned to supply international markets, while emerging importers such as South Africa, Kenya, Côte d’Ivoire and Namibia could create additional demand.
Three countries shaping Africa’s gas expansion
Three countries illustrate the different ways in which gas could reshape the region’s energy landscape: Côte d’Ivoire through domestic power generation, Nigeria through the expansion of production and LNG exports, and Mozambique through largescale export infrastructure and regional energy integration.
Côte d’Ivoire: linking gas to electricity demand
Côte d’Ivoire stands out because it already has an established gasto-power sector. The country’s experience offers a potential model for economies seeking to use domestic gas to meet growing electricity demand. Eni has advanced its Baleine oil and gas development through successive phases, with a third phase planned.
The project produces oil alongside associated gas, strengthening the potential contribution of domestic resources to the energy system. Rapidly rising electricity demand is also creating pressure to secure reliable gas supplies.
Agreements with Exmar for a floating storage and regasification unit (FSRU) arrangement point to the role imported LNG could play in complementing domestic production.
Côte d’Ivoire could therefore provide a useful model for combining domestic gas production, imported LNG and power generation to support economic growth.
Nigeria: expanding production while serving domestic consumers
Nigeria’s federally backed Decade of Gas initiative has gained momentum since 2023, supported by policy and fiscal measures intended to encourage investment and raise production. Several gas projects have reached final investment decisions, with further developments expected as the country seeks to expand supply for both exports and domestic consumption.
Nigeria LNG’s planned expansion towards 30 million tonnes per annum of capacity from 2027 is part of a broader effort to increase export earnings. At the same time, the country is targeting domestic gas production of 12 billion cubic feet per day by 2030.
Meeting both ambitions will require investment across the gas value chain, from production and processing to pipelines, power generation and industrial distribution. Nigeria could demonstrate how a major gas-producing economy can expand LNG exports while increasing supplies for domestic industries and smaller-scale LNG markets.
Mozambique: building a major LNG export hub
Mozambique is emerging as one of Africa’s most consequential gas investment destinations after years of delays associated with insecurity in the north of the country. Coral South, which began production in 2022, has established Mozambique as an LNG exporter.
Further expansion is under way or planned. Eni’s Coral North floating LNG project reached a final investment decision in October 2025, while construction on TotalEnergies’ Mozambique LNG project resumed in January 2026 after the lifting of force majeure.
The projects are expected to add substantial export capacity as they progress towards production. The proposed 18.6-milliontonne-per-annum Rovuma LNG development represents another major opportunity.
Its partners have been advancing preparations towards a final investment decision targeted for 2026, although the investment decision and the required approvals remain critical milestones. Together, these developments could establish Mozambique as a major global LNG supplier over the next decade.
But its potential extends beyond exports. Domestic gas could support electricity generation, industrial development and smaller-scale LNG distribution to neighbouring countries.
Pipeline supplies and regional power links could also help expand access to energy across southern and eastern Africa. With the right infrastructure, financing and regional agreements, Mozambique could become an important anchor for energy integration in the region.
Markets to watch
Beyond these leading producers, several countries face decisions that could shape their energy systems well into the 2030s. Ghana is seeking to strengthen its gas infrastructure as industrial demand grows. Planned pipeline developments and the potential entry of LNG imports through Tema could provide additional supply options, although the timing and commercial viability of new infrastructure will be decisive.
Namibia has attracted significant attention following major offshore oil discoveries in the Orange Basin. Gas development is more complicated because some associated gas may initially be reinjected to support oil production. A comprehensive gas master plan will be needed to determine how commercially recoverable gas can eventually support domestic energy and industry.
South Africa faces two interconnected challenges: developing gas-fired power generation and securing the LNG infrastructure needed to supply it. Additional gas-to-power capacity has been proposed as part of efforts to strengthen electricity supply.
But projects will depend on the availability and affordability of gas, the development of import terminals and pipelines, and the ability to secure reliable long-term supplies. South Africa must also consider the potential of its own offshore resources, including the Orange Basin, while recognising that exploration success does not automatically translate into commercially available gas.
Tanzania presents a particularly important case of the gap between resource potential and commercial development. The country began producing natural gas in 2004 and discovered substantial offshore resources from 2010 onwards.
The project’s progress towards a Host Government Agreement and the subsequent investment decision will be central to determining when Tanzania can begin exploiting its offshore resources on a large scale. The opportunity extends beyond LNG exports.
Tanzania could use gas to expand electricity generation, supply industries, support fertiliser production and develop compressed natural gas and smaller-scale LNG markets. But capturing these benefits will require commercial agreements, infrastructure investment, clear implementation timelines and a domestic market capable of absorbing additional production.
Turning domestic gas into economic growth
A further opportunity lies in converting gas already produced onshore into usable energy rather than treating it primarily as an upstream commodity. Compressed natural gas (CNG), small-scale LNG (SSLNG) and gas-to-power projects can connect gas resources to transport, businesses, industries and electricity consumers.
These options may be particularly relevant in markets where large export terminals are not commercially viable or where demand is dispersed across several locations. Countries including Botswana, Namibia, Nigeria, South Africa and Zimbabwe are exploring different approaches to using gas for domestic energy and industrial development.
The economics will vary from market to market. Projects need dependable supply, sufficient demand, appropriate infrastructure and financing structures that can support investment over the long term. Regional cooperation could also open markets that would be difficult to serve individually.
Smaller economies, including Lesotho, Eswatini, Mauritius and Zambia, may benefit from cross-border electricity trade or smaller-scale gas supply arrangements where the infrastructure and commercial case are viable. Uganda, meanwhile, could explore the use of associated gas to meet some of the energy requirements of its emerging oil industry.
These possibilities underline a broader point: Africa’s gas opportunity is not confined to the countries with the largest reserves. It also involves building the infrastructure and commercial relationships needed to connect producers with consumers.
ALSO READ: LNG project inches closer to implementation
The next phase of Africa’s gas growth
The outlook for 2027 and beyond will depend on how effectively African countries combine LNG exports with domestic gas development, smaller-scale distribution and gas-fired power generation.
The continent has substantial resources, growing energy needs and opportunities to develop industries that require reliable electricity and fuel.
But resources alone will not guarantee success. Governments will need to establish predictable regulatory frameworks, coordinate infrastructure development and create commercially viable markets. Investors will need confidence that projects can be completed on time, that contracts will be honoured and that revenues can support long-term operations.
Financing will be equally important. Large LNG developments require substantial capital, while domestic pipelines, power plants and distribution networks often depend on different financing models and revenue structures.
The strategic objective should therefore be broader than maximising gas production. It should be to connect gas resources to electricity generation, industrial activity, jobs and regional trade.
Africa’s next gas chapter will be determined not simply by how much gas it exports, but by how effectively it turns that resource into reliable energy, productive investment and sustained economic growth.