Europe’s aviation blacklist: Safety protection or a barrier to African airline expansion?
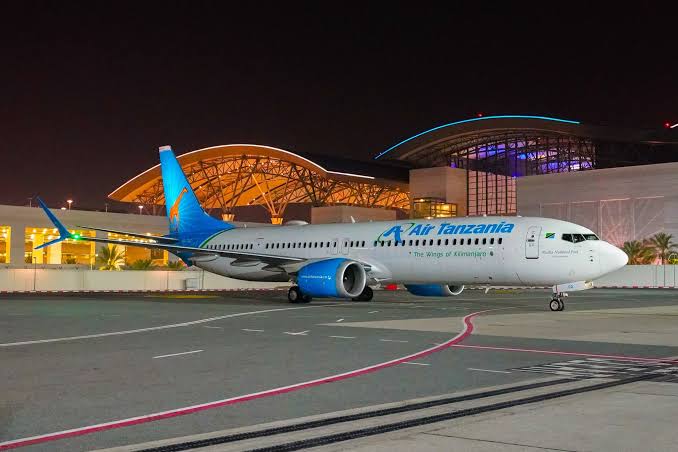
TANZANIA: THE European Union’s decision to maintain aviation safety restrictions on 12 African countries, affecting 87 individually named airlines, raises important questions about safety, regulatory standards, international market access, and the future competitiveness of Africa’s aviation industry.
The affected countries include Tanzania, Angola, the Democratic Republic of Congo (DRC), the Republic of Congo, Djibouti, Equatorial Guinea, Eritrea, Liberia, Libya, São Tomé and Príncipe, Sierra Leone, and Sudan. The latest reported update, published on November 17th this year, confirms that the restrictions remain in place.
Tanzania has 34 individually named carriers the highest number among the affected countries. Strategically, this development warrants serious examination, particularly as African countries and Tanzania in particular invest in airports, expand national airlines, improve regional connectivity, and seek to benefit from tourism, trade, and economic integration.
The central question is whether the restrictions are a proportionate application of international aviation safety standards or whether their broad application creates unintended barriers for African airlines seeking to expand internationally.
It is important, however, to distinguish between legitimate aviation safety concerns and the broader economic consequences of regulatory restrictions. Passenger safety must never be compromised, but African airlines, some of which have the newest aircraft, should not be denied market opportunities without transparent, objective, and independently verifiable assessments.
One key question remains: Is the EU decision technically justified? Based on safety and common knowledge, the EU Air Safety List was created to protect passengers by restricting airlines that fail to demonstrate compliance with international aviation safety standards.
The European Commission administers it, with support from the European Union Aviation Safety Agency (EASA) and aviation safety experts from EU member states. An important distinction is that the EU does not necessarily ban an airline because it failed an individual operational safety inspection.
It may instead impose a countrywide restriction if a national aviation regulator is considered unable to adequately oversee the airlines it certifies. As a result, airlines that have not been individually found unsafe may also be affected.
From a regulatory perspective, this approach has a sound basis. A country may have technically capable airlines, but if its aviation regulator cannot consistently inspect aircraft, certify operators, license personnel, enforce maintenance requirements, and monitor safety management systems, its overall oversight capacity becomes a concern.
Nevertheless, the proportionality of a countrywide restriction warrants scrutiny. Should a carrier that has independently demonstrated strong safety management systems face the same restrictions as an operator with significant operational deficiencies? This is where the debate becomes critical, and African leaders need to stand up.
A more differentiated approach, where possible, could allow airlines with independently verified compliance records to demonstrate their individual suitability for international operations while the regulator addresses broader institutional weaknesses.
The IOSA certification question—why are some airlines still affected? —may be the debate’s most important technical issue. The IATA Operational Safety Audit (IOSA) is an internationally recognised evaluation system that assesses an airline’s operational management and control systems.
It examines areas such as flight operations, operational control, aircraft maintenance, cabin operations, ground handling and safety management systems. Policymakers and the public should understand one important fact: IOSA registration is not the same as approval by a national aviation regulator or an exemption from the EU Air Safety List.
For example, the African Airlines Association’s 2025 annual report identifies both Air Tanzania Company Limited and Precision Air among Africa’s IOSA-registered airlines. Yet, both appear in the EU restrictions applying to Tanzanian-certified airlines.
From a policy point of view, one could ask: How can this happen? The answer lies in the difference between airline-level operational safety and state-level regulatory oversight. IOSA evaluates an airline’s operational management and control systems.
The national regulator oversees licensing, certification, surveillance, and enforcement across the aviation industry. ICAO assesses how the state fulfils its international civil aviation safety oversight obligations, while EASA separately evaluates third-country operators seeking authorisation to conduct commercial flights into the EU.
Therefore, an airline can retain IOSA registration even if the national regulator has deficiencies in its institutional capacity. This distinction is especially relevant to Tanzania.
The EU’s 2025 assessment identified shortcomings within the Tanzania Civil Aviation Authority (TCAA), including insufficient qualified technical personnel, weaknesses in human-resource planning, staff training, quality management, certification processes, and oversight of air carriers.
The EU’s assessment included a sample examination of Precision Air and Coastal Travels. Much as IOSA registration is important evidence of an airline’s safety-management capability, it cannot, on its own, show that the national aviation oversight system is functioning effectively as a whole.
Likewise, a regulator’s shortcomings should not prevent an airline’s individual safety record from being considered transparently. But broadly, what is driving Europe’s concern about the expansion of African airlines? It would be premature to conclude that Europe is deliberately restricting them out of fear of their commercial growth.
The European Commission’s published justification focuses on passenger safety, international standards, and inadequate regulatory oversight—not on competition with African airlines. However, the economic and competitive implications deserve attention.
For policymakers, four key dimensions deserve attention. The first is competition in international aviation markets. African airlines are gradually strengthening their fleets, expanding routes, improving airport infrastructure, and forming partnerships.
As they grow more competitive, they seek greater access to international passenger and cargo markets. Restrictions on access to European airspace can limit these commercial opportunities.
Second, protecting established aviation market positions. European airlines already have extensive international networks, established customer relationships, and access to major aviation hubs. Restrictions on African carriers may indirectly preserve these advantages by limiting direct competition. This is a possible economic consequence, not evidence that competition concerns motivated the EU’s safety decision.
Third, regulatory power and international market access. International aviation is governed by technical standards, but powerful aviation jurisdictions also shape market access through their regulatory systems. African countries need stronger technical and institutional capacity to engage with these systems on equal terms.
Fourth, the risk of unequal treatment. African airlines and regulators have a legitimate interest in knowing whether comparable safety deficiencies are assessed consistently across regions. Transparency about the evidence, methodology, appeal procedures, and removal criteria is essential to maintaining confidence in the system.
It is, therefore, important to distinguish legitimate safety regulation from protectionism. The existence of commercial consequences does not automatically prove that a safety restriction is commercially motivated. From an economic point of view, the economic implications of the restriction have consequences for Tanzania and Africa beyond the airlines themselves.
In Tanzania, the implications are particularly significant because aviation is a key component of the tourism economy. International connectivity supports the movement of tourists visiting Serengeti, Ngorongoro, Zanzibar, Kilimanjaro, and other destinations.
The country’s aviation expansion, including Zanzibar’s move towards its own airline, as recently stated by President Dr Hussen Mwinyi and investment in aircraft, airport infrastructure, and new facilities, must therefore be matched by equally strong improvements in safety regulation and operational oversight.
There is also a reputational impact. An EU-wide restriction can shape how international passengers, aviation financiers, aircraft lessors, insurers, and tourism operators view the sector, even if individual airlines have made substantial investments in safety improvements.
Is Africa being treated differently from other regions? A balanced assessment must recognise that the EU Air Safety List is not exclusively an African restriction. The June 2026 official update reported 154 banned airlines across 16 states.
ALSO READ: Air Tanzania launches direct Dar-Muscat flights to serve fast-growing tourism market
This included 126 airlines affected by inadequate national safety oversight, as well as airlines individually restricted for serious safety deficiencies. Russia alone accounted for 22 individually listed airlines. This suggests that the regulatory framework extends beyond Africa.
Still, the concentration of restrictions affecting African countries raises a legitimate policy question: why do so many African aviation authorities struggle to demonstrate effective regulatory oversight? What should Tanzania and African policymakers do given ongoing investment?
Rather than dismissing international safety concerns or simply protesting the restrictions, they should address technical weaknesses while demanding transparent and proportionate treatment.
Without delving into strategic interventions, Tanzania, in particular, should deepen engagement with ICAO, IATA, EASA, AFRAA, and other aviation authorities to strengthen regulatory capacity, technical training, and safety oversight systems.
Beyond increasing investment in aviation human capital, African countries should work through the African Civil Aviation Commission (AFCAC) and AFRAA to strengthen regional safety oversight, share technical expertise, and advance implementation of the Single African Air Transport Market (SAATM).
This would strategically mean a lot for the future of African aviation. The debate should ultimately shift from whether Europe fears African airline expansion to whether Africa has developed the institutional, technical, and financial capacity to compete effectively in the global aviation industry.
Africa has a growing aviation market, expanding tourism destinations, increasing demand for regional connectivity and significant opportunities in air cargo, logistics and passenger transportation. However, infrastructure investment alone cannot deliver a competitive aviation industry without internationally credible safety oversight.
The African Union’s Single African Air Transport Market presents an important opportunity to expand connectivity, reduce fragmentation, and build a more integrated continental aviation market. Achieving this ambition, however, requires harmonised regulations, mutual confidence in safety oversight, and consistent enforcement of international standards.
Tanzania should therefore treat the EU restrictions as both a regulatory challenge and an opportunity to modernise its aviation oversight institutions.
Questions European and African aviation authorities should answer to advance a constructive debate: If an airline is fully IOSA-registered, has a strong safety record, and complies with applicable international standards, what additional evidence must it provide to demonstrate its eligibility for international operations?
Or should countrywide restrictions automatically apply to every airline, including those that can demonstrate individual operational compliance?
More strategically, how transparent are the EU’s assessment criteria, and can affected African airlines independently challenge the evidence used against them?
Or, more importantly, how can Africa and Europe develop a more collaborative aviation safety framework that protects passengers while facilitating fair market access? Just as safety must be safeguarded, African aviation must also be given a fair opportunity to grow.
While the European Union’s aviation restrictions raise a legitimate safety concern, they also expose a broader structural challenge facing African aviation: the gap between expanding commercial airline operations and the capacity of national institutions to regulate them effectively.
Based on a critical examination of Europe’s aviation blacklist issued on 17 Nov 2026, the main contention is that Africa, and Tanzania in particular, should not be forced to choose between expanding aviation and ensuring aviation safety. Both are essential.
Rather than acting as an unwarranted barrier to market access, safety regulations should support competitiveness.
Because the future of African aviation should be determined by the quality, safety, efficiency, and competitiveness of its airlines rather than by geographic origin, African airlines must also recognise that international expansion requires demonstrable safety performance, robust corporate governance, and ongoing regulatory compliance.