Dar es Salaam transit cargo rises 17% as corridor competition shifts
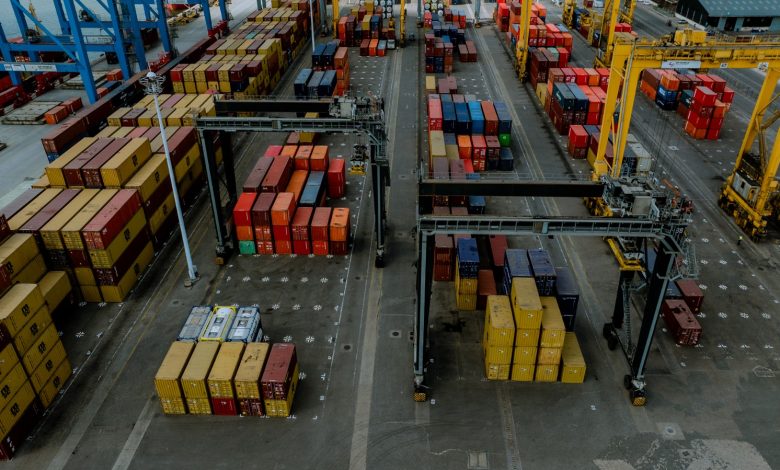
DAR ES SALAAM: Transit cargo through Dar es Salaam Port rose 17 percent to 14.61 million tonnes in the 2025/26 financial year, driven largely by stronger flows to the Democratic Republic of Congo, Zambia and Rwanda. The increase comes as investment at the port by concessionaire DP World, alongside government investment in Tanzania’s rail and road network, changes the options available to businesses moving goods between the Indian Ocean and inland markets.
The gains were uneven. DRC-bound cargo increased 30 percent to 7.77 million tonnes, giving the country more than half of Dar es Salaam’s transit traffic. Zambia remained one of the port’s largest markets at 3.41 million tonnes, while Rwanda-bound volumes rose 24 percent to 2.18 million tonnes.
That divergence matters. Dar es Salaam is competing for cargo whose owners can weigh different ports and corridors against cost, reliability and transit time, particularly in mining and manufacturing markets where delays can affect inventories and production schedules.
A busier port, with faster operations
The regional growth sits within a broader rise in activity at Dar es Salaam. Total cargo handled reached 33.71 million tonnes in 2025/26, up 21.5 percent from a year earlier, according to official port data reported this month.
Longer-term government figures point in the same direction. Cargo handled at Dar es Salaam rose from 16.27 million tonnes in 2020/21 to 27.76 million tonnes in 2024/25, while the average time container vessels spent at berth fell from about 10 days to three.
Part of the improvement at Dar es Salaam appears to have come from private investment in port operations by TEAGTL and global operator DP World, which operates ports and terminals in more than 80 locations worldwide. Its logistics network handles around 10 percent of global trade volumes.
At Dar es Salaam Port’s Terminal 1, operated by DP World, recent reports indicate that cargo discharge times for comparable operations have fallen from more than 300 hours to under 28 hours since operations began in April 2024 under a 30-year concession. The improvement points to a significant change in the speed at which cargo can be moved through the terminal.
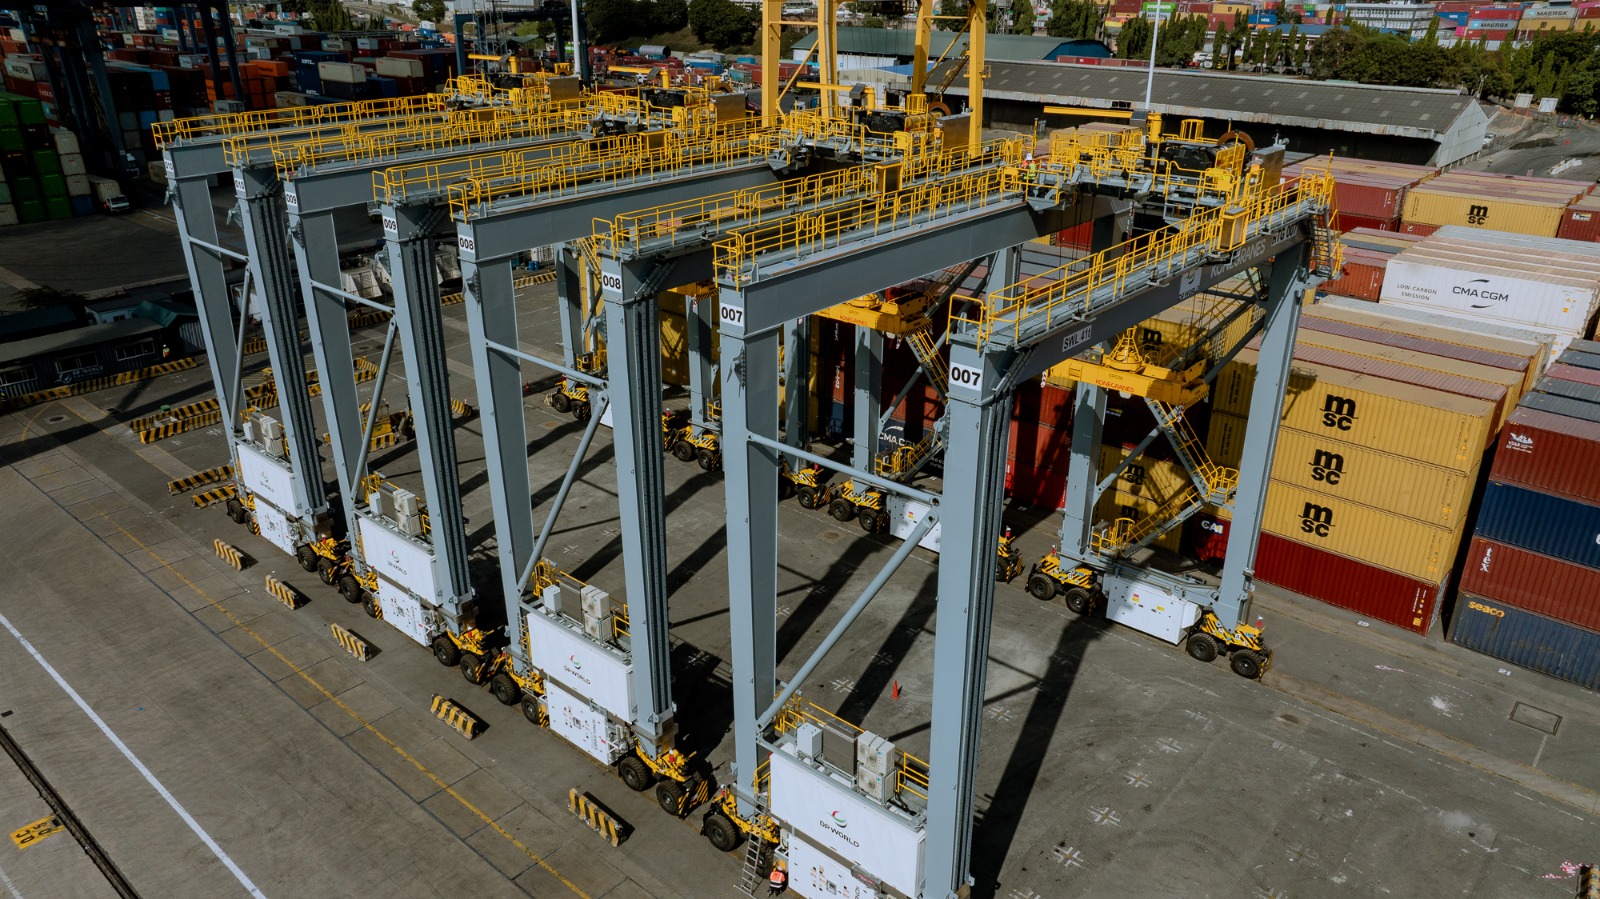
The port operator had deployed USD123 million by April 2026 on equipment, infrastructure, technology and operating systems. Investment has been made in cranes, cargo-handling systems, yard infrastructure and two gates connecting the port with Nelson Mandela Road. Notable among the investments are eight new diesel-electric Rubber Tyred Gantry Cranes (RTGs), specialised equipment used for handling containers, which were commissioned in June.
Container traffic has also risen, with four consecutive record-breaking months of throughput. The terminal handled 44,001 containers in May, 45,856 in June, 46,582 in July and 48,793 in August, according to data from regulators. This contrasts with pre-2024 monthly performance of between 8,000 and 13,000 containers.
Changes in the cargo mix are visible in vessel calls as well. Dar es Salaam has received larger and more specialised vehicle carriers, including the 240-metre M/V RAMHAN, which DP World says discharged close to 7,900 heavy-duty vehicles in just over 27 hours. This has come alongside increased handling of dry bulk, general cargo and roll-on/roll-off traffic.
Government plans also envisage additional dry-bulk equipment intended to lift handling capacity by 65 percent for cargo such as wheat, sulphur and fertiliser. This expansion will add to Dar es Salaam Port’s current average wheat discharge rates of more than 12,000 tonnes per day, which are already among the highest in the region.
The test increasingly lies beyond the quay
Faster discharge alone cannot determine whether Dar es Salaam wins more regional cargo. Once goods leave the ship, customs processing, inland storage, rail availability, road conditions and border performance begin to determine the time and cost faced by cargo owners.
Tanzania began commercial freight operations on the Standard Gauge Railway between Dar es Salaam and Dodoma in July 2025, while construction continues on sections intended to extend the network westwards. A planned freight terminal at Morogoro is designed to connect rail cargo with road transport serving domestic and neighbouring markets.
Kwala is another part of that inland push. The dry port is already receiving trains from Dar es Salaam and is designed to handle about 300,000 containers a year, with neighbouring countries including DRC, Zambia and Rwanda allocated space within the development.
Zambia’s route is receiving separate attention through the rehabilitation of TAZARA. Physical works under the revitalisation programme moved forward in July, with construction beginning on a new operations control centre and training centre in Dar es Salaam. Authorities are seeking to restore the railway’s role in linking the Tanzanian coast with Zambia and wider Southern African markets.
Road bottlenecks are also being addressed. At Tunduma, the border approach is being widened from one lane to four after congestion became a recurring constraint for trucks moving between Tanzania, Zambia, DRC and other Southern African markets.
The administrative side is changing alongside physical infrastructure. TASAC is preparing to introduce a new Maritime Transport e-Regulatory System in September, allowing maritime service providers to process licences, registrations and supporting documents online rather than relying on largely paper-based procedures.
DP World’s regional role was illustrated again this month through its work with the United Nations World Food Programme, which moved 5,000 tonnes of rice through Dar es Salaam for onward distribution to Burundi, DRC and Rwanda. The shipment shows how changes at the waterfront connect with a much longer logistics chain extending deep into neighbouring markets.
Capacity is only part of the contest
The rise in DRC and Rwanda traffic suggests that more cargo owners are using Dar es Salaam as regional port capacity and inland connections improve. Zambia’s decline, however, is a reminder that infrastructure investment does not automatically translate into additional market share. Possible factors include American ownership of some mines and ongoing negotiations over border fees and taxation with the Tanzanian government.
The commercial contest will increasingly be decided across the full corridor: how quickly a vessel is handled, how efficiently cargo clears the port, whether rail or trucks are available, how borders perform and whether customers can predict when goods will arrive.
Dar es Salaam has added capacity and reduced some of its most visible operating delays, but the harder test is whether those gains can now be carried consistently from the coast to customers hundreds or thousands of kilometres inland.