BoT guarantees unlock 2.1tri/- loans for businesses
DAR ES SALAAM: THE Bank of Tanzania (BoT) has issued credit guarantees worth 1.6tri/- to facilitate access to loans totalling 2.1tri/- across various sectors of the economy, aimed at improving access to financing for businesses and entrepreneurs.
The guarantees provided through the Export Credit Guarantee Schemes (ECGS), two government-backed credit guarantee schemes managed by the central bank to support viable businesses that struggle to secure loans due to inadequate collateral.
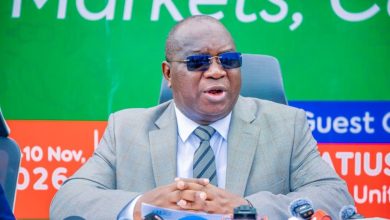
Speaking during a seminar for journalists, BoT’s Senior Financial Analyst Ms Gloria Chellunga said the initiative was designed to enable entrepreneurs with commercially viable projects to access financing from banks and other financial institutions despite lacking sufficient assets to meet conventional lending requirements.
“Some businesses have viable projects and meet the lending requirements of banks, but they fail to secure financing because they do not have sufficient collateral. “These schemes were established to bridge that gap and enable such businesses to access loans,” she said.
Ms Chellunga said the initiative aimed at helping viable businesses, particularly exporters and small and medium enterprises (SMEs), overcome collateral shortages that often prevent them from accessing financing from commercial banks and other financial institutions she said the government established two schemes of ECGS established in July 2002 and the Small and Medium Enterprises Credit Guarantee Scheme (SMECGS), introduced in September 2005 purposely to improve access to credit for businesses and entrepreneurs with insufficient collateral.
The schemes designed to bridge the gap between viable business opportunities and the financing needed to turn them into sustainable enterprises.
ALSO READ: BoT hails the 33 percent growth in private sector lending, 2.5 decline in non-performing loans
Under the arrangement, applications for guarantees are submitted to BoT by banks or financial institutions seeking to lend to customers who qualify for financing but have insufficient collateral.
The central bank assess the application to establish whether the proposed project is financially viable and capable of generating sufficient revenue to repay the loan.
“After satisfying the project viability, we approve the guarantee and allow the respective bank to proceed with lending to its customer,” she added.
Despite the financing made possible through the schemes, participation by SMEs remained relatively low, although they are among the main intended beneficiaries.
She attributed the situation partly to the large number of businesses operating informally, making it difficult for them to meet the legal and administrative requirements necessary to access guarantees through the schemes.