BoT holds rate at 6.25pc in fourth quarter
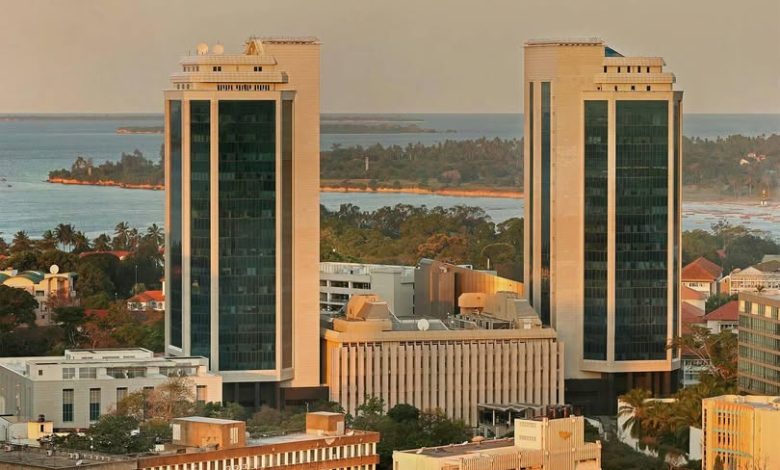
DAR ES SALAAM: BANK of Tanzania (BoT) kept its Central Bank Rate (CBR) at 6.25 per cent for the fourth quarter of 2026 as inflation remained within target and private-sector credit surged.
BoT Governor Emmanuel Tutuba announced the decision at a press conference yesterday, following a meeting of the Monetary Policy Committee (MPC) on Wednesday.
He said the MPC decided to maintain the rate as it is convinced that the central bank’s restrictive monetary stance was still working through the economy even as private-sector credit expands at its fastest pace.
“The MPC said the 6.25 per cent Central Bank Rate is appropriate because it is continuing to dampen underlying inflationary pressures while supporting economic growth,” he said.
Inflation was 4.3 per cent in August, within the central bank’s 3-5 per cent target range, although it has been rising from an average of 4.1 per cent in the quarter through June.
At the same time, credit to the private sector grew by an average 32.5 per cent in the quarter through September, highlighting the unusual combination of rapid lending growth and a less accommodative monetary policy stance.
“The current restrictive monetary policy stance [is] appropriate as it continues to filter through the economy,” he said.
The decision comes as Tanzania adopts a new statistical picture of the economy following the rebasing of national accounts. The National Bureau of Statistics changed the GDP base year from 2015 to 2019, lifting nominal GDP for 2025 to 234.1 tri/- ($92.3 billion) from 230.1tri/- in Mainland Tanzania under the previous series.
Zanzibar’s nominal GDP rose to 9.2tri/- from 7tri/-, he said. The revised data also show that economic momentum remains strong.
Mainland Tanzania expanded 6 per cent in the first quarter, with growth estimated at more than 6 per cent in the second and third quarters.
Zanzibar grew 6.7 per cent in the first quarter and is estimated to have exceeded 7 per cent in the following two quarters. Mr Tutuba said the external position has come under some pressure.
The currentaccount deficit widened to 2.5 per cent of GDP in the year through September from 2.4 per cent in the year through June, as higher global commodity prices, freight costs and geopolitical tensions weighed on the economy.
Still, stronger exports of gold, tourism and manufactured goods helped cushion the impact of higher imports, he said.
Foreign-exchange reserves remained above 6 billion US dollars, with import cover at 4.3 months, exceeding the national minimum of four months. The global backdrop is making the BoT cautious.
The MPC said the conflict in the Middle East has disrupted energy and fertiliser supply chains and stalled disinflation in many economies, with oil prices at times exceeding 100 US dollars a barrel.
From the banking sector, Equity Bank Tanzania Managing Director Isabella Maganga, representing the Tanzania Bankers Association (TBA), welcomed the decision to maintain the rate.
She said the decision reflected the Bank’s choice of stability at a time of global uncertainty.
“This translates to confidence and resilience of our economy,” she said.
Analysts say the CBR influences the broader cost and availability of credit in the economy.
By holding it at 6.25 per cent, the BoT is not adding another layer of monetary tightening while businesses and households continue to access credit at a rapidly expanding pace.
For businesses, the decision provides greater certainty for investment and financing decisions.
For households, it reduces the risk of an immediate further increase in borrowing costs. But the 32.5 per cent credit growth also gives the MPC something to watch.
If rapid lending begins to feed stronger domestic demand and eventually puts upward pressure on prices, the case for tighter monetary policy could strengthen.
For now, however, inflation at 4.3 per cent suggests that the rapid expansion in credit has not yet translated into broad inflationary pressure sufficient to warrant another rate increase.
The decision therefore suggests that the MPC is not reacting mechanically to strong credit growth. Instead, it appears to be weighing credit conditions alongside inflation, economic growth and external pressures.